USD.AI: A real lending business. But does $CHIP get any of it?
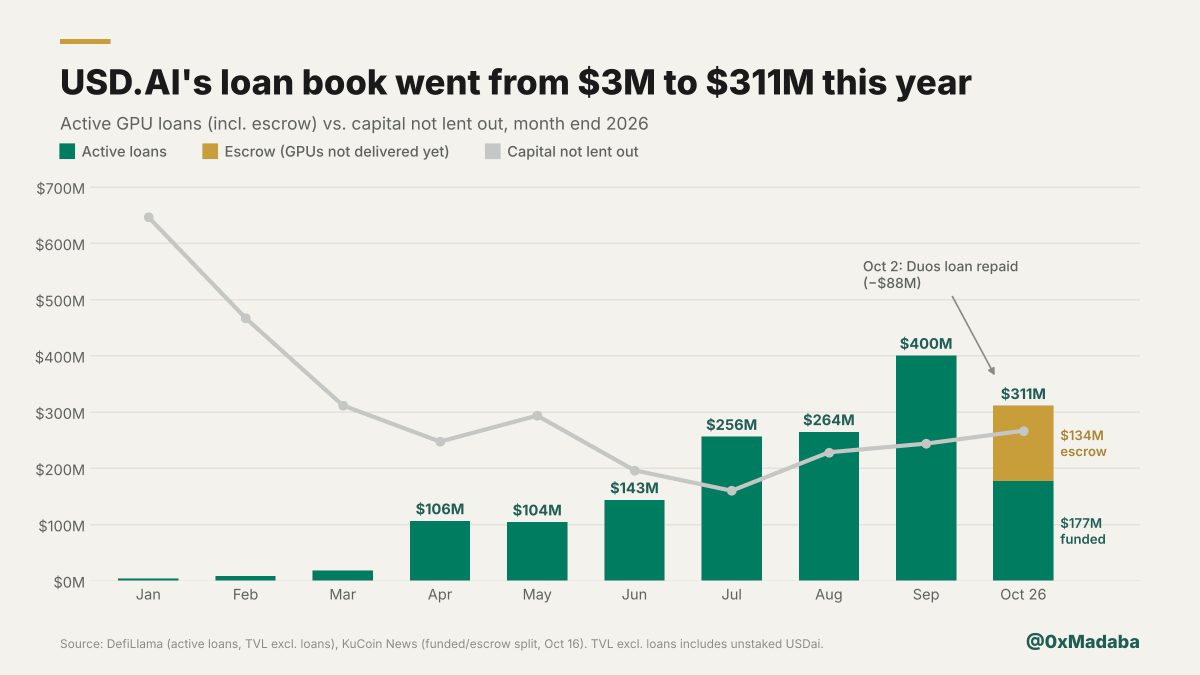
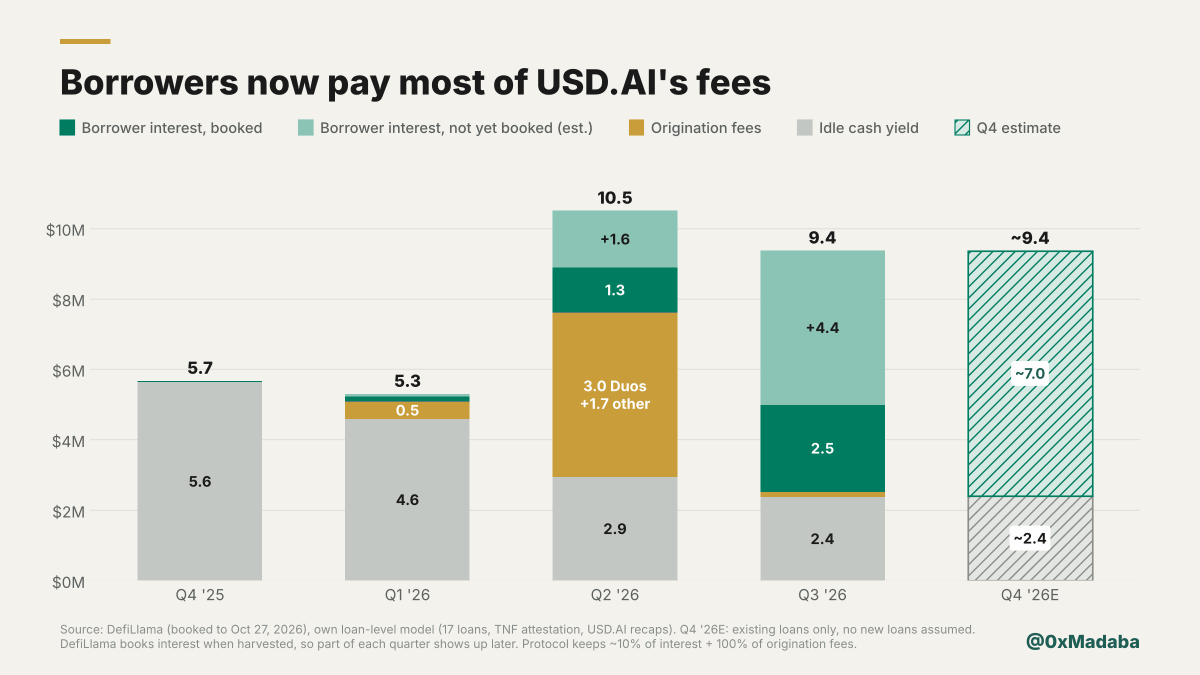
USD.AI's loan book went from $3M to $311M this year with ~$35-40M in annualized fees. CHIP holders get $0 of it, so far.
Research snapshot · 27 Oct 2026
The business
USD.AI lends to smaller GPU operators against their hardware, at ~72% LTV on average and without reported defaults. About 90% of fees go to depositors, so protocol revenue is more like $4-9M a year.
The token
CHIP is a governance token without automatic revenue share. On market cap it is priced roughly like Maple, on FDV 4-8x more expensive, with only ~20% circulating and a big unlock in April 2027.
The upside
It depends on whether the company or governance starts sending value to the token. The $1M buyback the day before publication was the clearest step in that direction.
Updates since publication
USD.AI proposed programmatic CHIP buys from sUSDai net interest, about $3.7M a year by my estimate. Origination fees move to USDAI Inc.
Post on X ↗A $106M facility for NexGen Cloud through GLX, with Silver Point and Victory Park lending alongside.
Post on X ↗
Sources & related reading
The main thesis of this piece is followed in the track record →
Keep reading
Top onchain protocols by revenue multiple: November update
Eleven tokens ranked by market cap over annualized 30-day revenue, from PUMP at 2.7x to LINK at 163.3x, with a median of 14.1x and the biggest revenue movers.
Read more →
Launchpads: revenue resilience and token valuations
Pons and StonkFun out-earned Pump in September, then lost over 90% of their revenue. Why both became more expensive relative to revenue while PUMP got cheaper.
Read more →